APR, Interest Rate, and Fees: What Each Term Means
An interest rate describes the cost of borrowing a balance, fees are separate charges, and APR is a broader comparison figure whose calculation depends on the product and applicable rules.
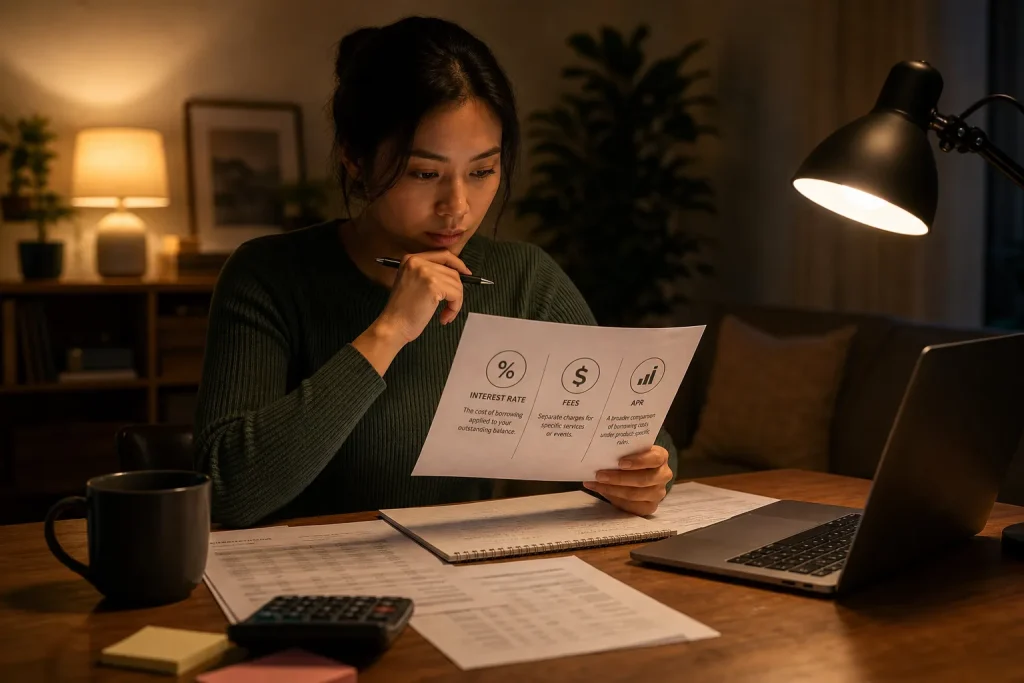
A loan offer can place its interest rate in large type, list fees elsewhere, and show the annual percentage rate (APR) farther down. These figures are related, but they answer different questions. Reading them side by side helps you understand the offer and identify what still needs clarification.
The interest rate applies to the borrowed balance
The interest rate is the charge for borrowing money, expressed as a rate over time. In a typical loan, interest accrues on the outstanding balance according to the agreement. As you repay principal—the amount borrowed—the balance used to calculate future interest generally falls.
The rate alone does not describe the full cost. The amount borrowed, payment schedule, timing of payments, and whether the rate can change all matter. A lower rate cannot be compared fairly with another offer until you understand how each loan is structured.
For a credit card, the agreement may list different rates for purchases, cash advances, or balance transfers. It may also explain when a promotional rate ends and what rate applies afterward. Check the terms for the kind of borrowing you plan to do rather than assuming one rate covers every transaction.
Fees have their own terms and triggers
Fees are charges a lender or card issuer may apply for specified services or events. Depending on the product, examples can include an origination fee, a balance-transfer fee, or a late-payment fee. The offer or account agreement should explain whether a fee applies, when it is charged, and how it is calculated.
A fee is not the same as interest. Interest is generally tied to borrowing a balance over time; a fee is tied to a stated charge or event. A fee might be deducted from loan proceeds, added to a balance, or charged separately. That affects how much money you receive and what you may owe.
Read the fee details alongside the rate. Identify which charges are one-time and which may recur, what triggers them, and whether the agreement describes a way to avoid them. If the wording is unclear, ask the lender how the charge would appear on your statement or closing documents.
APR offers a broader, product-specific comparison
APR expresses borrowing costs as an annual rate calculated under rules that depend on the product and jurisdiction. It may account for the interest rate and certain charges, but it does not necessarily include every fee or describe every cost you might encounter. Consult the offer’s disclosures to see how APR is calculated for that particular credit product.
For some loans, specified lender charges are included in the APR calculation, while other costs may be excluded. Credit-card APR disclosures also follow product-specific rules; do not assume that every account fee or charge is reflected in the APR. Costs such as late-payment charges may be disclosed separately. The applicable agreement and required disclosures determine what is included.
APR can help compare similar offers with similar repayment terms. It is less useful on its own when offers differ substantially in repayment length, rate variability, fee treatment, or the amount you expect to borrow. A fixed APR does not mean every possible charge is fixed, and a variable rate may change under conditions described in the agreement.
Compare the terms behind the headline figures
For each offer, write down the interest rate, APR, and listed fees. Note whether the rate is fixed or variable, which balance or transaction it applies to, and when payments are due. For a loan, review the repayment schedule and the total repayment shown under the stated terms. For a card, check how interest is calculated and which actions could trigger separate charges.
If the offer lists fees but does not explain how they relate to APR, ask the lender which charges are included in the calculation and which are not. Confirm whether a quoted rate depends on conditions that may not apply to you. These questions help you compare the written terms rather than relying on one attractive number.
A hypothetical comparison of two loan offers
Hypothetical worked example: Suppose a borrower needs a particular amount available for a planned expense and receives two fixed-rate personal-loan offers. Offer A lists a lower interest rate but has an origination fee deducted from the proceeds. Offer B lists a higher interest rate and no origination fee.
The borrower first checks each offer’s APR disclosure and asks whether the origination fee is included in that calculation. Next, they confirm the amount each lender would deposit, then compare the repayment schedules and stated total repayment. The resulting tradeoff is clear: Offer A provides less money upfront because of the deduction, while Offer B avoids that deduction but may involve more interest over repayment. The borrower still needs to assess whether each offer provides enough usable funds and fits their repayment needs; the APR alone does not settle that choice.
Use each figure to answer a different question
The interest rate describes how the lender charges for an outstanding balance. Fees identify separate charges and the conditions attached to them. APR provides a broader comparison calculated under product-specific rules, but it is not a complete forecast of every cost or a substitute for reading the agreement.
Before accepting credit, make sure you can explain each figure in plain language and know what could change it. If the disclosures are difficult to interpret, ask the lender for clarification. For a consequential borrowing decision, a qualified financial professional can help assess how the agreement fits your circumstances.
Keep exploring
Questions to Ask Before Adding Credit to a Household Plan
Compare three ways to handle a household credit decision: borrow now, wait and prepare, or choose…
Why a Credit Check May Ask You to Confirm Your Identity
An identity prompt can be a routine part of an application, but you should understand who…