Questions to Ask Before Adding Credit to a Household Plan
Compare three ways to handle a household credit decision: borrow now, wait and prepare, or choose a smaller commitment. The right questions concern total cost, timing, contractual responsibility, and what happens if circumstances change.
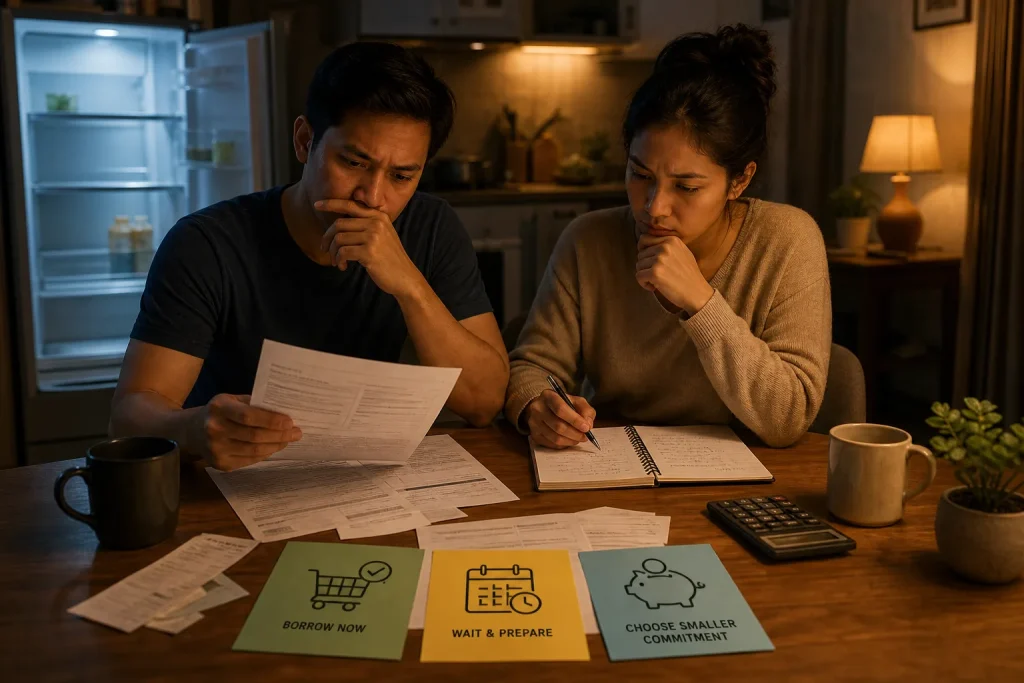
A refrigerator stops cooling just as rent and a car repair compete for the household’s available cash. A store offers financing, and a bank card is within reach. The immediate need is clear, but the best response is not necessarily to borrow at once: compare the cost of acting now with the consequences of waiting or choosing a less expensive replacement.
Credit moves a cost into future pay periods; it does not remove the cost. Before applying, make the options concrete: what each one requires, when money would be due, who would be legally responsible under the agreement, and what could make the plan harder to manage. The purpose is not to forecast every change, but to choose with the terms and tradeoffs in view.
Define the need before comparing offers
Start by describing what the credit would pay for and how soon it is needed. A failed refrigerator may require prompt attention, while an upgrade may be postponed. The urgency can change the balance between waiting and borrowing, but it does not make unclear terms easier to assess.
Separate the purchase from its financing. For each offer, identify the amount to be financed, any deposit, disclosed fees, payment dates, and the terms that apply after a promotional period. Ask the lender or merchant for written clarification if a fee, rate, or schedule is unclear. Compare the written terms rather than relying on a checkout summary or a verbal assurance.
Then ask how the proposed payment fits alongside essential household commitments. If the plan works only when income arrives exactly as expected and no other expense intervenes, recognize that as a constraint. A budget can help show where pressure may arise; it cannot decide whether a particular credit agreement is suitable for everyone involved.
Borrow now only when the terms and need are clear
Borrowing promptly may be reasonable when the expense cannot sensibly wait and the household understands the agreement. It can leave cash available for other immediate needs, but adds an obligation that will compete with future bills. Convenience, an approval, or a sales deadline is not a substitute for reading the terms.
Check whether the payment or rate can change, what happens after an introductory offer ends, and what charges may apply if a payment is late or missed. Ask whether early repayment has conditions and how payments are applied when an account has balances with different terms. The agreement and the lender’s written disclosures are the appropriate sources for those details.
Be precise about responsibility. When two people apply, each should understand what the contract says about their own obligations; a private household arrangement about who pays or handles chores may help coordinate day-to-day tasks, but it may not change contractual responsibility. The effect depends on the agreement and applicable law. If that responsibility is uncertain or consequential, ask the lender to explain the contract and consult a qualified professional where needed.
Wait when time can improve the decision
Waiting may suit a purchase that can be delayed, or a household that needs time to understand the offer. During the pause, compare written terms, ask questions, consider repair or lower-cost alternatives, and see whether setting aside money changes the amount that needs financing.
Delay also has costs. A household may have to manage without a necessary item, or a problem could worsen. Treat a sales deadline as a reason to ask how long an offer remains available, not as proof that borrowing is necessary. Distinguish an urgent need from pressure to decide before the terms are clear.
For a simple comparison, place the proposed payment alongside essential bills and the household’s expected income dates. If the payment would land when several other obligations are due, ask whether the lender offers another schedule or consider waiting. If there is no workable schedule, do not treat an optimistic income forecast as a solution.
Reshape the purchase when the full commitment feels strained
A less expensive model, a repair, a partial cash payment, or another financing arrangement may address the need with a different commitment. Whether any option is better depends on its actual terms. A lower monthly payment alone does not establish a lower total cost; the repayment period or other conditions may differ.
Compare alternatives on equal terms: amount owed, payment timing, fees, and what happens when any introductory period ends. If using a card already in the household, include its existing balance and planned use in the decision. An available credit limit is not spare income. For a store plan, read the agreement for terms that could change the amount due or the payment schedule.
Household coordination can make the plan easier to follow, but keep it distinct from contractual liability. People may agree who will watch for a notice or contact the lender if a payment problem arises. That practical division does not necessarily alter what an applicant owes under the contract.
Use concrete questions to distinguish the options
- How urgent is the purchase? If it cannot reasonably wait, compare available terms for a timely replacement; if it can wait, consider delaying while clarifying the offer or setting aside money.
- What amount would be owed under each offer? If the written terms state the amount and applicable fees, compare them; if an item is unclear, ask for written clarification before applying.
- When would payments be due? If the dates fit around essential bills, assess the commitment against the rest of the budget; if they collide, ask about another schedule or reconsider the offer.
- Who would be responsible under the contract? If each applicant understands their contractual role, continue comparing the options; if responsibility is uncertain, ask the lender and seek qualified advice where appropriate.
- What could change the amount or timing due? If the offer clearly explains rate changes, promotional terms, and late-payment consequences, include those conditions in the comparison; if not, request the missing terms or decline to rely on the offer.
- What alternative meets the need? If a repair or less expensive model is available and workable, compare its cost and timing with borrowing; if not, return to the financing options with the unresolved tradeoffs stated plainly.
- What would happen if an urgent cost appeared? If the household has a realistic response that does not depend on an uncertain future income change, include it in the plan; if it has no workable response, consider waiting, reducing the purchase, or asking the lender about options before committing.
Work through a hypothetical refrigerator decision
Consider an invented household facing a failed refrigerator. For this example only, suppose the household has enough cash for a basic replacement but using all of it would leave little room for an essential bill. A store offers financing with an introductory period, and one household member has a bank card with an existing balance. The store has not yet clarified its fees or the terms after the introductory period. These are hypothetical conditions, not typical terms for any lender.
First, the household writes down the actual offers available to it: the store plan’s stated payment dates and the unanswered questions about fees and later terms; the card’s written rate and payment terms, alongside its existing balance; and the cash price and delivery timing for a basic model. It asks the store for the missing terms in writing. Until those arrive, the store plan remains an unknown rather than a comparable option.
Next, the household places each known payment against its upcoming essential bills and expected income dates. It finds that using cash for the basic model would leave too little room for an already scheduled bill. It also sees that adding the refrigerator purchase to the card would increase an existing obligation. Those observations do not settle the choice, but they make the tradeoff visible: cash preserves a simpler purchase but strains the near-term budget; the card adds to a balance; the store plan cannot yet be judged.
Finally, suppose the store supplies written terms, and the household confirms that the payment schedule fits its budget, while the card terms do not fit as comfortably. The household can then compare the store plan with waiting briefly for another cash arrangement or a repair. If the store still cannot clarify the later terms, the household can rule out that offer and decide between the remaining known options. The resulting decision is not that one type of credit is universally best; it is a choice based on this invented household’s need, available terms, and cash-flow tradeoff.
Choose an option the household can explain
Before committing, the people affected should be able to say what the credit covers, what the contract requires, when payments fall due, and which conditions could change the plan. Borrowing now may fit an urgent expense and clear terms. Waiting may fit a flexible purchase or an offer that remains unclear. A smaller purchase may address the need while limiting the commitment.
Keep the written offer and agreement where the relevant people can find them, and record any household arrangement separately from the contract. If the terms remain unclear, or the legal or financial consequences are significant, pause and ask the lender or a qualified professional for help. Even when every option has a drawback, identifying which drawback the household can manage is a useful basis for choosing.
Keep exploring
Why a Credit Check May Ask You to Confirm Your Identity
An identity prompt can be a routine part of an application, but you should understand who…
A Simple Routine for Keeping Credit Paperwork in Order
A modest filing habit can make statements and account correspondence easier to find when a question…